 Diana Foster
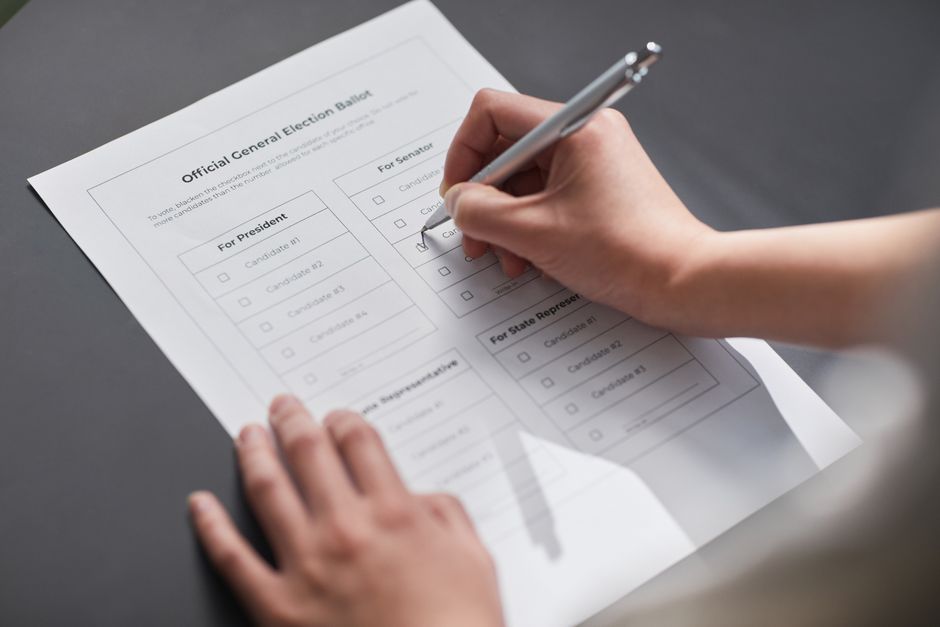
Most homeowners think of insurance as a private transaction: you pick a policy, you pay your bill, end of story. What surprised me when I left claims adjusting and started watching this from the outside is how completely that mental model misses the actual mechanics. Your premium isn’t just a number some actuary invented. It’s shaped, sometimes dramatically, by a single elected or appointed official in your state capitol whose name you probably can’t remember. And this November, that’s about to matter in a way it rarely has before.
Home insurance premiums have climbed 46% nationally since 2021, roughly three times the rate of general inflation, according to Insurify’s March 2026 analysis. The average annual premium hit $2,948 in 2025 and is projected to reach $3,057 by end of 2026. That’s not a rounding error. For a lot of households, that’s a car payment they didn’t budget for. And voters are noticing: a July 2026 Insurify poll of 1,500 Americans found that 58% say rising insurance costs will make them more likely to turn out in the midterms. That’s an extraordinary number for a policy issue most people couldn’t have named two years ago.
- Home insurance premiums rose 46% since 2021, averaging $2,948 annually in 2025.
- Four states elect insurance commissioners in November 2026: California, Georgia, Oklahoma, and Kansas.
- 58% of voters say rising insurance costs will increase their 2026 midterm turnout.
- Only 17% of voters know state commissioners regulate insurance rates.
- Governors in 39 states appoint commissioners, making 36 governor's races indirectly consequential.
The Four States Where Your Vote Goes Directly to Your Premium
California, Georgia, Oklahoma, and Kansas are all holding insurance commissioner elections this November. I’ll be honest: I didn’t expect this race to show up in so many states simultaneously, but here we are, and the timing is brutal for policyholders. All four states recorded meaningful rate increases in 2025.
Oklahoma’s 24% single-year jump is the kind of number that gets people to the polls. Kansas at 15% isn’t far behind. Georgia and California look milder in comparison, but California’s race carries extra weight for structural reasons: Commissioner Ricardo Lara is term-limited and cannot run again, creating an open seat with no incumbent advantage. State senators Jane Kim and Ben Allen advanced from the June 2026 primary to the November runoff, according to Insurance Business Mag. The policy positions they’ve staked out on rate approval timelines and insurer exit rules could meaningfully affect whether carriers stay in the California market at all, which is not a theoretical concern given what’s happened there since the Los Angeles wildfires.
The Hidden Variable: 36 Governor’s Races
Helpful resource: Kidde Carbon Monoxide and Propane Detector is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
The four elected-commissioner states get the attention, but here’s where it gets more complicated. In 39 states, the insurance commissioner isn’t elected. The governor appoints them. Which means the 36 governor’s races happening this November are, indirectly, also insurance races. A governor who prioritizes consumer protection over carrier profitability will appoint a commissioner who leans hard on rate increase requests. A governor who worries about market exits, and some legitimately should, will appoint someone more permissive.
This isn’t a partisan point. Both sides of that tradeoff have real consequences. I spent years watching what happens when carriers decide a market isn’t worth the regulatory friction: they leave, coverage becomes scarce, and homeowners end up in state-run insurers of last resort that nobody actually wants to use. The politics are messy. The outcomes are real.
The Knowledge Gap That’s Driving Everything
Here’s the stat that stuck with me most from the recent research. Only 17% of voters correctly identified that state insurance commissioners regulate rates, per an August 2026 InsuranceNewsNet report. Seventeen percent. That means the overwhelming majority of people who are furious about their premiums don’t know who actually has the power to do something about it.
This isn’t surprising if you’ve worked inside the industry. Insurance regulation is genuinely obscure. It doesn’t generate the kind of coverage that, say, gas prices do, even though the financial impact is comparable for many families. What’s changed in 2026 is that the pain has gotten acute enough that people are asking the question. The education, though, is still catching up.
| State | Commissioner Selection | 2025 Rate Increase | November Stakes |
|---|---|---|---|
| Oklahoma | Elected | 24% | Commissioner race on ballot |
| Kansas | Elected | 15% | Commissioner race on ballot |
| Georgia | Elected | 9% | Commissioner race on ballot |
| California | Elected | 5% | Open seat; Kim vs. Allen runoff |
| 39 other states | Governor-appointed | Varies | Governor races carry indirect weight |
What Homeowners Should Actually Be Watching
If you’re in one of the four states with a commissioner race, the candidates’ positions on a few specific things will matter more than their general rhetoric. Rate filing timelines: how long does a carrier have to wait for approval before a rate increase takes effect? Prior approval versus file-and-use rules: can a carrier start charging the new rate immediately and face review later? And market conduct: will the commissioner’s office actually investigate claims handling, or focus only on solvency?
These aren’t exciting campaign talking points. You’re unlikely to hear them in a debate. But they’re the levers that directly connect the commissioner’s office to your renewal notice. I’d suggest looking at endorsements from state consumer advocacy organizations, not because endorsements are definitive, but because those groups have usually done the homework on where candidates actually stand on the technical stuff.
If you’re in one of the 36 governor’s race states, it’s worth spending fifteen minutes looking at what the current commissioner has done on rate oversight and asking whether the governor candidates have said anything specific about insurance market stability. Most haven’t. That silence is itself informative.
The research here is mixed on how much any single commissioner can actually move the needle on premiums in the short term. Carriers set rates based on reinsurance costs, claims trends, and catastrophe modeling that no state official fully controls. But over a four-year term, a commissioner’s posture absolutely affects the market: who stays, who exits, how aggressively increases get challenged, and whether consumers get any relief in disputed claims situations. That’s not nothing. Given where premiums are headed, it might be the most consequential state-level vote most homeowners cast this year. Talking to an independent insurance agent or a consumer advocate familiar with your state’s regulatory environment is worth the time before November, because this stuff is genuinely complicated and your situation is specific to you.
Sources
- Why home insurance prices are quietly becoming a 2026 midterm flashpoint (August 3, 2026)
- Home Insurance Is the Stealth Election Issue of 2026 Midterms (July 31, 2026)
- How the 2026 Midterms Could Reshape Home Insurance Affordability (July 1, 2026)
- Home insurance is the stealth political issue of 2026 (August 3, 2026)
- Property Insurance Could Become THE Issue of the 2026 Midterm (August 4, 2026)
- Who’s running for insurance commissioner in CA’s 2026 election? (August 2026)
Photo: Edmond Dantès via Pexels
This article is for general informational purposes only and does not constitute insurance advice. Coverage details, exclusions, and costs vary significantly by insurer, policy type, and location. Always review your policy documents and consult a licensed insurance professional for advice specific to your situation.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Kidde 10-Year Battery Smoke & CO Detector (~$32), Dual smoke and carbon monoxide detector with 10-year sealed battery, no battery replacement needed for a decade.
- Ring Alarm 8-Piece Security Kit (~$199), Professional-grade DIY home security system with optional 24/7 monitoring, top way to qualify for insurance discounts.





