 Laura Martinez
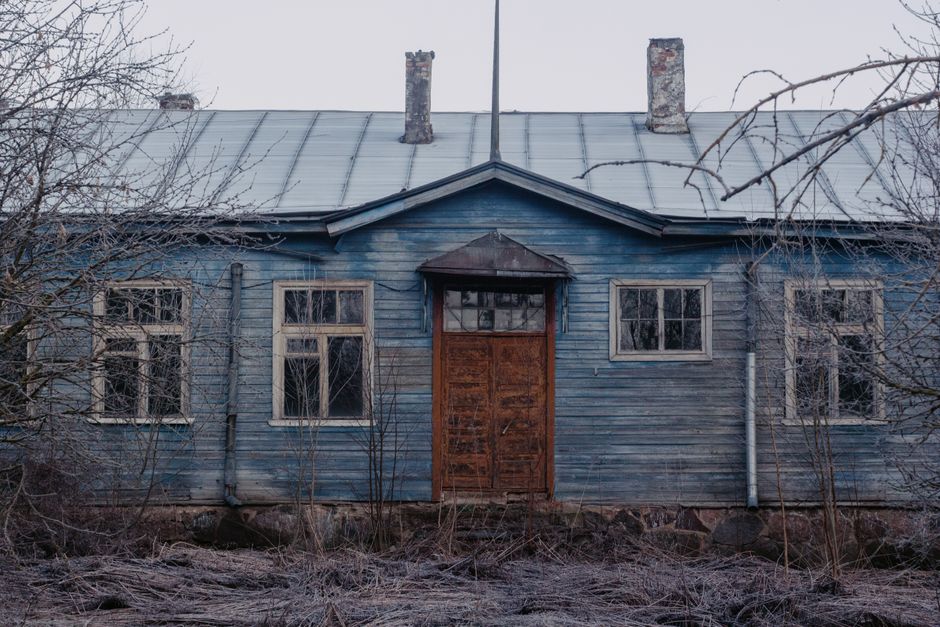
Most homeowners don’t know their standard policy stops protecting them after 30 to 60 days of vacancy. Not pauses. Stops.
I’ll be honest: I didn’t fully appreciate how aggressively insurers apply vacancy clauses until I started reviewing denied claims on the other side of the desk. We’re talking about a provision buried in the definitions section of virtually every standard homeowner policy, and most people discover it exists only after they file a claim and get a letter explaining why they’re getting nothing. That letter is not fun to receive.
What surprised me was how common the underlying situations are. A job relocation that takes longer than expected. An inherited property that can’t sell in a slow market. Snowbird homeowners who stretch their winter trip by a few extra weeks. A renovation that ran over schedule. These aren’t rare edge cases. They happen constantly, and the coverage gap they create is real.
- Standard homeowner policies typically void coverage after 30-60 consecutive days of vacancy.
- Unoccupied home insurance (also called vacant home insurance) fills this gap, usually at 1.5x to 3x the cost of a standard policy.
- "Unoccupied" and "vacant" are legally different terms with different coverage implications, your insurer uses both.
- Most vacant property policies exclude vandalism, water damage, and glass breakage unless you pay extra riders.
- Proactive steps (regular inspections, water shutoff, security cameras) can meaningfully reduce your premium.
The Difference Between “Vacant” and “Unoccupied” (It’s Not Semantic)
Insurers aren’t using these words loosely. The distinction has real financial consequences.
An unoccupied home still contains furniture and personal property. It looks lived-in; someone just isn’t there right now. A vacant home is empty. No furniture, no personal effects, nothing except the structure itself. Insurers treat these differently because the risk profile genuinely differs: a furnished home signals that someone has reason to return, which tends to correlate with more frequent check-ins and maintenance. A vacant home, by contrast, is more attractive to squatters, copper thieves, and vandals, and problems like a slow plumbing leak can go undetected for weeks.
The Insurance Information Institute notes that vacant properties face substantially elevated risk across fire, water damage, and liability compared to occupied homes. That’s not marketing language. In my 14 years reviewing claims, vacant property losses were almost always more severe than comparable losses in occupied homes, simply because nobody caught the problem early.
Here’s where it gets tricky: your policy’s definition of “vacant” may not match the dictionary’s. I’ve seen policies that consider a home “vacant” if it lacks working utilities, even if the owners left furniture behind. Read your actual policy language, not what the agent summarizes over the phone. Ask for the definitions section specifically. The question to ask: “How does this policy define vacant, and what triggering conditions apply to the vacancy clause?”
Why Standard Coverage Fails (And When)
Helpful resource: First Alert BRK 3120B Hardwired Smoke and CO Detector is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
The 30-to-60-day vacancy window isn’t random. It reflects underwriter judgment about when a property’s risk profile meaningfully shifts. After that window closes, most standard policies either void coverage entirely or reduce it to a named-perils shell that covers almost nothing useful.
According to data tracked by the National Association of Insurance Commissioners (NAIC), vacancy-related claim denials are one of the more common sources of homeowner disputes. The NAIC’s consumer resources by state can show you your state’s complaint ratios by insurer, which is genuinely useful if you’re shopping around.
The specific exclusions that kick in fastest are usually:
- Vandalism and malicious mischief
- Glass breakage
- Water damage from internal plumbing (the slow-leak category)
- Liability for injuries on the premises
Fire and structural damage from named perils typically remain covered longer, but even that depends on the carrier. I’ve reviewed claims where a homeowner assumed fire coverage continued during a six-month vacancy and was badly wrong.
Worked example: A reader in Phoenix emailed me last spring after inheriting her mother’s home. The estate took nine months to settle. During that time, a pipe failed in the second bathroom. Damage estimate from the contractor: $34,000. Her claim was denied because the standard policy had a 60-day vacancy clause, and the home had been unoccupied for seven months. She’d never been told to get a separate product. Her agent never flagged it. That $34,000 came out of the estate.
What Unoccupied and Vacant Home Insurance Actually Covers
Vacant property insurance is a specialty product, and it’s underwritten differently than standard homeowner policies. A few things worth knowing:
Most vacant policies are written on a named-perils basis, meaning only the risks explicitly listed are covered. Standard homeowner policies are often open-perils (all risks covered except those excluded). That’s a meaningful difference. If the peril isn’t named in your vacant policy, assume it’s not covered.
Coverage periods are usually sold in 3-month, 6-month, or 12-month blocks. You can’t typically buy a vacant policy for a two-week gap. And because insurers view these properties as higher-risk, they’ll often require a property inspection before binding coverage, sometimes charging $75 to $150 for it.
The pricing varies considerably by property characteristics, location, and how much coverage you buy. Here’s a realistic comparison based on industry data and my own experience reviewing these products:
| Property Situation | Typical Annual Cost | Coverage Type | Key Exclusions to Watch |
|---|---|---|---|
| Standard occupied homeowner policy | $1,200 to $2,400 | Open-perils (HO-3) | Flood, earthquake |
| Unoccupied rider added to existing policy | $200 to $600 added | Extends standard policy 3-6 months | Carrier-specific; confirm in writing |
| Standalone vacant home policy (basic) | $1,500 to $3,500 | Named-perils only | Vandalism, water damage, glass |
| Standalone vacant home policy (broad form) | $2,500 to $5,500 | Broader named-perils | Flood, earthquake, liability if excluded |
| Builder’s risk / renovation policy | $2,000 to $6,000+ | Structure under construction | Contents, completed work varies |
Ranges reflect national averages as of July 2026 and will vary significantly by state, property value, and insurer. Always get at least three quotes.
How to Actually Get This Coverage
Here’s the process I’d walk through, step by step, because the shopping experience for vacant home insurance is not like buying a standard policy online.
Step 1: Contact your current insurer first. Some carriers will extend your existing policy with a vacancy endorsement, often cheaper than a standalone product. Ask specifically: “Do you offer a vacancy permit or unoccupied home endorsement?” If they say no, move on.
Step 2: Estimate your coverage period honestly. If you think you need three months, ask for six. Extending mid-term is possible but sometimes involves requalification. Underestimating is a common and expensive mistake.
Step 3: Contact specialty insurers. The standard carriers that dominate personal lines often won’t write vacant home policies, or they’ll decline properties over a certain value. Look for surplus lines carriers, which operate through licensed surplus lines brokers. Your state’s insurance department website can point you toward licensed brokers in your area.
Step 4: Get the inspection done quickly. Many carriers won’t bind coverage until someone physically checks the property’s condition. Schedule it fast; uninsured gaps are real.
Step 5: Document the property’s condition. Take a timestamped video walkthrough before you leave. If you file a claim later, the insurer will want to know what pre-existed. I can’t stress this enough: I reviewed claims where pre-existing damage arguments killed a legitimate payout. A home inventory app won’t help with the structure itself, but a document safe with printed timestamped photos will. (The site may earn a commission from linked products.)
Worked example: A homeowner in Chicago listed a property for sale in January and couldn’t close until August. She called her carrier in February when she realized the house had been vacant for five weeks. They added a vacancy endorsement for $380 for six months. In June, a water heater failed. The claim paid out $8,700. The endorsement fee was well worth it. More importantly, she asked the right question before the gap opened, not after.
Reducing Your Risk (And Your Premium)
Insurers price vacant home policies based on their assessment of what will go wrong and when. You can influence that assessment.
The factors that consistently lower premiums: regular property inspections (many carriers require proof of monthly walkthroughs), a monitored alarm system, water shutoff at the main line, someone with a key who can respond to alerts, and a property management company on record. Water leak sensors placed near appliances and under sinks are inexpensive and some carriers explicitly acknowledge them. (The site may earn a commission.) A monitored fire extinguisher station doesn’t hurt either.
I used to review inspection checklists submitted by policyholders trying to qualify for lower rates. The ones that worked weren’t elaborate. Dated photos of the main shutoffs, the electrical panel, and the entry doors. A signed log showing someone physically walked the property every 30 days. That documentation shifted the carrier’s risk calculation visibly.
The research on exactly how much these steps reduce premiums is mixed. I’ve seen carriers discount 5% for a monitored alarm; I’ve seen others ignore it entirely. Ask each carrier specifically what credits they offer and what documentation they need. Don’t assume.
Worked example: A renovation project in Austin ran four months over schedule. The homeowner had a builder’s risk policy, but the contractor paused work for six weeks while waiting on materials. The insurer considered that pause a vacancy trigger. The homeowner hadn’t hired anyone to do regular inspections. When a burst pipe caused $19,000 in damage, the carrier partially denied the claim, paying $11,200 based on a shared-fault argument around the inspection gap. A $150 monthly property management check-in would have cost $900 over six months and almost certainly would have caught the problem and preserved the full claim.
Sources
- Insurance Information Institute (III): Industry data on homeowner policy exclusions and vacant property risk factors
- National Association of Insurance Commissioners (NAIC): State-level complaint data, consumer tools, and insurer complaint ratios by state
- National Fire Protection Association (NFPA): Data on structure fire loss rates in unoccupied vs. occupied properties
- Insurance Services Office (ISO): Standard policy form language for HO-3 and vacancy clause definitions (industry reference, available through licensed agents)
- State insurance department bulletins: Most states publish guidance on specialty coverage requirements; search “[your state] department of insurance vacant property”
Photo: Plato Terentev via Pexels
This article is for general informational purposes only and does not constitute insurance advice. Coverage details, exclusions, and costs vary significantly by insurer, policy type, and location. Always review your policy documents and consult a licensed insurance professional for advice specific to your situation.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Kidde 10-Year Battery Smoke & CO Detector (~$32), Dual smoke and carbon monoxide detector with 10-year sealed battery, no battery replacement needed for a decade.
- Ring Alarm 8-Piece Security Kit (~$199), Professional-grade DIY home security system with optional 24/7 monitoring, top way to qualify for insurance discounts.





