 Carl Brooks
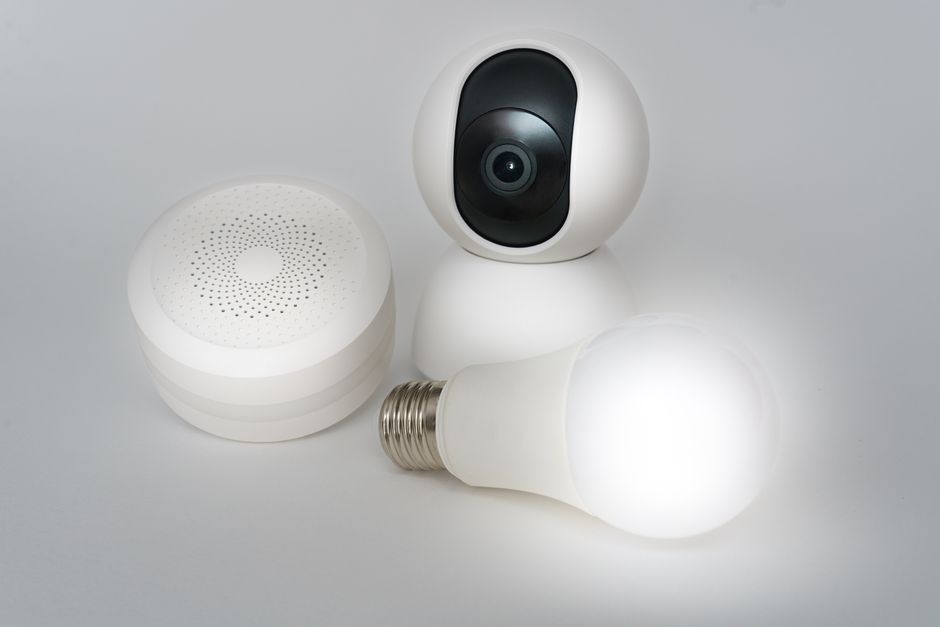
Forty percent. That’s the discount ceiling some insurers will actually quote you if your home is decked out with qualifying smart devices. I’ve seen the internal pricing models. I’ve sat in the meetings where underwriters talk about risk reduction data. And I’ll tell you honestly: most homeowners are leaving real money on the table not because the discounts don’t exist, but because nobody ever told them how to ask for them.
You might be wondering whether this applies to your policy, your insurer, your ZIP code. Fair questions. The answer is almost always “it depends,” which I know is frustrating to hear. So let me give you the real picture, not the marketing version.
Smart home discounts are genuinely available from most major carriers today, but they’re inconsistently advertised, unevenly applied, and buried under eligibility conditions that vary by state. What one insurer calls a “connected home discount” for a $35 water leak sensor, another insurer doesn’t acknowledge at all. As of August 2026, this space is still maturing, and that actually works in your favor if you know where to push.
- Smart home discounts range from about 2% to 15% per device category, with whole-home setups earning up to 40% at some carriers.
- Water leak sensors offer the highest ROI relative to cost, often paying for themselves in premium savings within 8 months.
- Most discounts require professional monitoring contracts, not just device ownership.
- You must proactively request these discounts, carriers rarely apply them automatically at renewal.
- Stacking multiple device discounts is possible, but your total discount is usually capped (commonly around 20-25%).
Where the money actually hides
Here’s what I tell people when they ask where to start: water. Not security cameras, not smart locks. Water.
Water damage is the single largest driver of homeowner claims by volume. According to the Insurance Information Institute, water damage and freezing account for nearly 24% of all homeowner claims, and the average payout per water claim has climbed past $12,000 in recent loss years. Insurers know this. Their actuaries have run the numbers on how much a $35 leak sensor changes their expected loss on a given property. The answer is: enough to give you a discount for installing one.
Leak sensors like the Flo by Moen or a basic Govee water detector (which runs about $12 per unit) are the fastest path to a concrete discount at the lowest possible cost. Flo by Moen goes further: it monitors your entire main supply line for anomalies and can auto-shut water off. Several carriers will give you a named discount for whole-home shutoff systems specifically, sometimes 8-10% on your dwelling coverage alone.
Smoke and CO detectors connected to a monitoring center come second. Fire claims are less frequent than water claims but far more expensive per incident, and insurers treat monitored smoke detection very differently from standalone detectors. The word “monitored” is doing a lot of work there. If it’s not sending signals to a central station that dispatches fire services, many carriers won’t count it toward the discount at all. I learned this the hard way reviewing a claim where a homeowner thought their Nest Protect qualified. It didn’t, because they never enrolled in a monitoring plan.
Security systems are third, and honestly, this is where the marketing noise gets loudest. Companies like ADT, SimpliSafe, and Ring Alarm all advertise insurance discounts prominently. Those discounts are real. But they’re usually in the 2-5% range for burglary-related coverage, which is a small slice of your total premium. Don’t let a security system salesperson tell you it’ll slash your bill. It won’t, not by itself.
What the numbers actually look like side by side
Helpful resource: First Alert BRK 3120B Hardwired Smoke and CO Detector is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
Discount ranges vary by carrier and state, but here’s a realistic composite picture based on what I observed across years of working with pricing teams and what’s currently reported by the major carriers and independent research groups as of 2026:
| Device Category | Typical Discount Range | Monitoring Required? | Estimated Device Cost | Avg. Payback Period |
|---|---|---|---|---|
| Whole-home water shutoff (e.g., Flo by Moen) | 8-15% | Sometimes | $500-$700 installed | 6-14 months |
| Water leak sensors (single zone) | 2-5% | No | $12-$50 | 4-10 months |
| Monitored smoke/CO detectors | 5-10% | Yes | $150-$300 + monitoring fee | 12-18 months |
| Monitored security system | 2-8% | Yes | $200-$600 + monthly | 18-30 months |
| Smart thermostat (select carriers) | 1-3% | No | $130-$250 | 24-36 months |
| Combined/connected home package | Up to 20-40% | Yes (usually) | Varies by bundle | Varies |
That payback period column is the one I’d stare at. Water sensors are almost always the fastest return, which matches everything I saw during my time reviewing claims.
The stacking question (and the cap nobody mentions)
You might be wondering: can I add up all these discounts and get 30% off? Technically yes. In practice, almost every carrier applies what’s called a maximum schedule credit, which limits how much your total smart home discounts can stack. That cap is usually 20-25%, though a handful of carriers will go higher for full connected-home enrollments that pipe data directly into their platforms.
Here’s a scenario that plays out more often than you’d think:
Homeowner in Columbus, Ohio installs a Flo by Moen whole-home shutoff, enrolls in SimpliSafe with professional monitoring, and adds three Govee leak sensors in the basement and laundry room. Calls insurer. Insurer quotes 12% for the shutoff system, 5% for the monitored security, and 2% for the sensors. Total claimed discount: 19%. Cap kicks in, actual applied discount: 18%. Annual premium was $1,640, so the savings come to about $295 a year. Devices and first year of monitoring cost roughly $950. Break-even is around 39 months.
That’s a legitimate, real-world outcome. Not $3,000 in savings. Not pennies either.
The thing carriers don’t advertise
Most of these discounts are not applied automatically. Not at purchase, not at renewal. You have to ask. I cannot stress this enough, because in 14 years of reviewing claims and later talking to policyholders, I watched this pattern repeat constantly: people bought the devices, assumed their insurer knew, and got nothing.
The process is usually this: install device, collect proof (receipt, monitoring confirmation number, sometimes a photo or installation certificate), call your agent or log into your carrier’s portal, and submit documentation through whatever form they use. Some carriers have started integrating with device manufacturers directly. State Farm has partnerships with certain alarm companies. Liberty Mutual has had their RightTrack-adjacent home programs. If your carrier offers a dedicated connected-home enrollment, that’s the faster path.
The Insurance Information Institute’s consumer resources are worth checking for carrier-by-carrier context, and your state’s insurance department (find yours at the NAIC’s state map) can tell you what discounts are filed and approved in your state. That matters. A discount a carrier advertises nationally may not exist in your state’s approved rate schedule.
One more thing I’d add: if you’re renovating or building new, the IBHS home fortification guides outline device and construction standards that some carriers use directly in their discount eligibility criteria. Worth reading before you buy anything.
Sources
- Insurance Information Institute (III): Industry data on claim types, frequency, and average payouts by peril category
- National Association of Insurance Commissioners (NAIC): State-level insurance regulation, approved rate filings, and consumer complaint data
- Insurance Institute for Business & Home Safety (IBHS): Research on home fortification standards and risk mitigation tied to loss reduction
- J.D. Power 2025 Home Insurance Study: Consumer satisfaction data and carrier discount transparency ratings
- III Report, “Homeowners and Renters Insurance” (2025): Claim frequency and severity breakdowns by peril, used for water damage statistics cited above
Photo: Jakub Zerdzicki via Pexels
This article is for general informational purposes only and does not constitute insurance advice. Coverage details, exclusions, and costs vary significantly by insurer, policy type, and location. Always review your policy documents and consult a licensed insurance professional for advice specific to your situation.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Kidde 10-Year Battery Smoke & CO Detector (~$32), Dual smoke and carbon monoxide detector with 10-year sealed battery, no battery replacement needed for a decade.
- Ring Alarm 8-Piece Security Kit (~$199), Professional-grade DIY home security system with optional 24/7 monitoring, top way to qualify for insurance discounts.





