 Diana Foster
Most homeowners assume their insurance will rebuild their house after a total loss. That assumption is wrong often enough that I spent a decade watching it shatter people at the worst possible moment. The policy in the drawer says “replacement cost.” The check that arrives covers maybe 70 cents on the dollar. The gap between those two things has a name, and understanding it could save you six figures.
Standard replacement cost coverage rebuilds your home up to the dwelling limit you chose when you bought the policy. That limit is a number you probably picked years ago, maybe with help from an agent using a per-square-foot calculator that hasn’t been updated since lumber was cheap. Guaranteed replacement cost (GRC) is different: it promises to rebuild your home fully, period, regardless of what that costs, even if reconstruction blows past your stated limit. Some insurers call it “extended replacement cost” or “unlimited replacement cost,” and the distinctions between those matter more than most agents will tell you.
- Standard replacement cost caps your payout at your policy limit, even if rebuilding costs more.
- Guaranteed replacement cost (GRC) covers full rebuild costs above your limit, with no stated ceiling.
- Extended replacement cost typically adds only 20-50% above your limit , not the same as GRC.
- Construction costs have risen sharply; policies written before 2022 are especially likely to be underinsured.
- GRC is not universally available; some high-value, coastal, or older homes can't qualify.
What “Guaranteed” Actually Means (and What It Doesn’t)
Here’s where I’d get it wrong at first, and I say that as someone who reviewed claims professionally: I assumed “guaranteed” was mostly marketing language. It’s not, but it comes with conditions most agents skim past.
To qualify for GRC coverage and actually collect on it, you typically have to meet three requirements your insurer will hold you to:
- Your dwelling limit must be set at or near the insurer’s estimated replacement cost when the policy is written. They’re not going to guarantee unlimited coverage if you deliberately underinsured the home to save on premium.
- You must accept automatic inflation adjustments annually. Refuse those increases and you may void the guarantee.
- You must report major renovations or additions promptly. Add a 600-square-foot addition and don’t tell your insurer, and they can deny the GRC promise on the grounds that the home being rebuilt isn’t the home they agreed to cover.
I’ve seen claim denials on all three of those grounds. The second one catches people especially off guard. The letter comes every year showing a small premium increase tied to an inflation adjustment, some policyholders call to opt out to save $40, and they’ve just quietly dismantled the most valuable part of their coverage.
Extended vs. Guaranteed: The Comparison That Actually Matters
Helpful resource: Kantek Portable Filing System and Document Organizer is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
These two terms get used interchangeably in marketing materials. They are not the same thing.
| Coverage Type | How It Works | Typical Cap Above Limit | When It’s Enough |
|---|---|---|---|
| Standard Replacement Cost | Pays up to your stated dwelling limit | None (limit is the ceiling) | When your limit accurately reflects rebuild costs |
| Extended Replacement Cost | Pays a fixed percentage above your limit | Usually 20%-50% over limit | Minor cost surprises; modest inflation gaps |
| Guaranteed Replacement Cost | Pays full rebuild cost regardless of limit | No stated ceiling | Total losses; major post-disaster cost spikes |
| Actual Cash Value | Pays replacement cost minus depreciation | N/A (pays less than rebuild cost) | Rarely sufficient for total losses |
A concrete example of why this matters: A homeowner in Austin, Texas carries a $380,000 dwelling limit on a policy written in early 2020. After a fire in 2026, contractors quote $590,000 to rebuild, reflecting current labor and materials costs. Extended replacement cost at 25% would pay $475,000, leaving her $115,000 short. Guaranteed replacement cost would pay the full $590,000.
Scenario: Texas homeowner, $380K limit, total loss in 2026 → Extended replacement cost (25%) pays $475K → Gap of $115,000 still owed by homeowner. Scenario: Same homeowner with GRC → Insurer pays full $590K rebuild → Gap: $0.
That’s not a rounding error. That’s a second mortgage.
How Underinsurance Happens So Fast
The Insurance Information Institute has tracked the gap between insured values and actual construction costs for years, and the numbers aren’t flattering to the industry. Construction costs increased dramatically starting around 2021, with lumber, labor, and materials all spiking. Policies written before those increases are especially exposed. If your dwelling limit hasn’t been meaningfully adjusted in the last few years, there’s a real chance you’re carrying a number that made sense in a different market.
The IBHS (Insurance Institute for Business & Home Safety) publishes home fortification guides that include notes on construction cost benchmarks; their regional rebuilding cost data is often more current than what your insurer’s internal calculator spits out. Worth a look before your next renewal.
The honest problem is that standard inflation adjustments, even when you accept them, often lag actual construction inflation. A 3-4% annual adjustment looks fine on paper and falls short in a year when contractor rates jump 12%. GRC is the only option that doesn’t require you to predict the future accurately.
Who Can and Can’t Get It
GRC isn’t available to everyone, and insurers are selective. Broadly speaking, newer homes in lower-risk areas are easiest to qualify. The harder cases:
Older homes with custom or non-standard features are a problem because “guaranteed” is harder to price when nobody builds plaster walls or old-growth fir floors anymore. Coastal properties in hurricane-prone states face availability issues because post-disaster reconstruction costs spike regionally in ways that make open-ended commitments expensive to underwrite. Very high-value homes sometimes get pushed toward surplus lines carriers that offer extended replacement cost but not true GRC.
If you’re in one of those categories and can’t get GRC, push hard for the highest extended replacement cost percentage your insurer offers (50% is better than 25%), and get an independent appraisal of your rebuild cost. That appraisal matters. The $350 you spend on an independent replacement cost estimate is cheap compared to what you’d lose in a claim dispute.
A document safe rated for fire and water damage is a small investment worth making before a disaster, not after. Keep your appraisal, home inventory, and policy documents somewhere they’ll survive what they’re supposed to document.
The Home Inventory Problem Nobody Talks About
Guaranteed replacement cost covers the structure. Your personal property is a separate coverage line, and most people are underinsured there too, but through a different mechanism: they never completed a home inventory.
I’ve seen GRC pay out perfectly on the dwelling and then watched a family argue for months over $40,000 in personal property contents because they couldn’t document what they owned. A home inventory app (like Encircle or the III’s free home inventory checklist) takes a few hours and eliminates that fight entirely. A water leak sensor won’t help you here, but it’s worth mentioning: preventing the claim beats winning the argument after. (The site may earn a commission from product links.)
What to Ask Before You Renew
Current as of August 2026, the questions worth putting directly to your agent or insurer are:
Does my policy carry true guaranteed replacement cost, or extended replacement cost? Get the exact language from the declarations page, not the sales summary. What are the conditions that could void the guarantee? Ask for them in writing. When was my dwelling replacement cost estimate last updated, and by what method? If the answer is “our internal calculator,” ask whether an independent appraisal would be accepted. What’s the notification requirement for renovations?
One small operational note: when you call to ask these questions, the customer service rep will often put you on hold to check. That pause is a signal. A genuinely clear policy shouldn’t require research to explain.
Sources
- Insurance Information Institute (III): Industry data on homeowner coverage types, replacement cost definitions, and underinsurance statistics.
- Insurance Institute for Business & Home Safety (IBHS): Regional construction cost benchmarks and home fortification guides.
- National Association of Insurance Commissioners (NAIC): Regulatory guidance on policy language standards and consumer complaint data by coverage type.
- CoreLogic Hazard & Risk Management Report (2025): Annual tracking of insured value versus reconstruction cost by region.
- Marshall & Swift/CoreLogic Residential Cost Handbook: Industry-standard residential replacement cost estimation methodology used by insurers and independent appraisers.
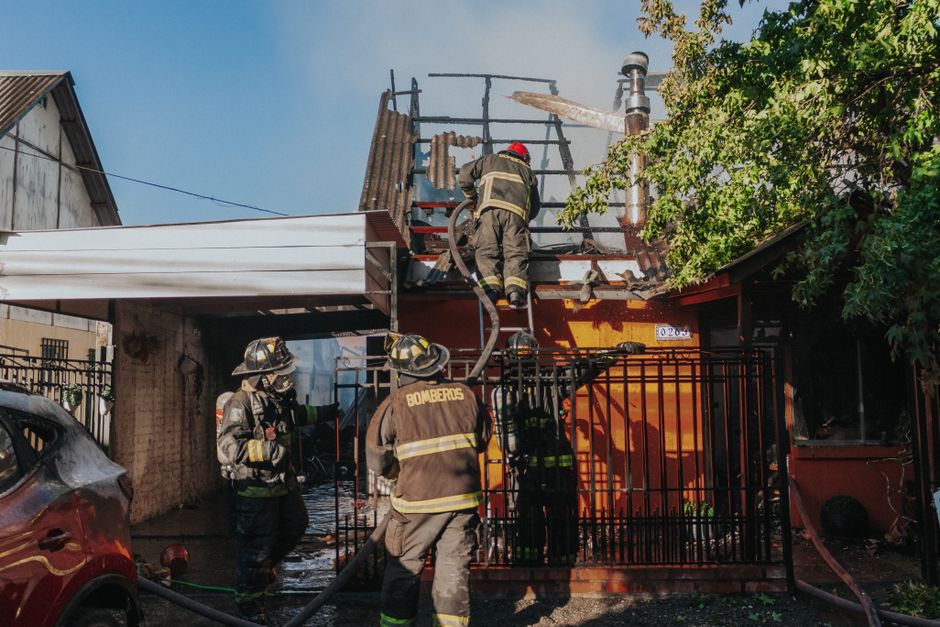
Photo: Oscar Sánchez via Pexels
This article is for general informational purposes only and does not constitute insurance advice. Coverage details, exclusions, and costs vary significantly by insurer, policy type, and location. Always review your policy documents and consult a licensed insurance professional for advice specific to your situation.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Kidde 10-Year Battery Smoke & CO Detector (~$32), Dual smoke and carbon monoxide detector with 10-year sealed battery, no battery replacement needed for a decade.
- Ring Alarm 8-Piece Security Kit (~$199), Professional-grade DIY home security system with optional 24/7 monitoring, top way to qualify for insurance discounts.





