 Carl Brooks
Most homeowners read their policy once, file it in a drawer, and assume they’re covered. They’re not wrong about the basics. But the gap between what they think they have and what they actually have? That’s where I spent 14 years of my professional life, sitting across from people who’d just had the worst week of their year and were about to have a worse conversation.
The exclusions section of a standard HO-3 policy is not a footnote. It’s closer to half the document, and it’s written in language designed to be technically clear while remaining practically opaque to anyone who didn’t go to law school. Let me fix that.
- Standard HO-3 policies exclude floods, earthquakes, sewer backup, and gradual damage, all four require separate coverage or endorsements.
- Mold claims are routinely denied if the insurer can show the source was a long-term, unaddressed leak rather than sudden water damage.
- "Ordinance or law" exclusions can leave you paying tens of thousands in code-upgrade costs after a covered loss.
- Home-based business equipment is typically capped at $2,500 under standard policies, often a fraction of its actual replacement cost.
- Reviewing your declarations page annually, not just at purchase, is the only way to catch coverage that's drifted out of sync with your actual risk.
The Exclusions That Catch People by Surprise
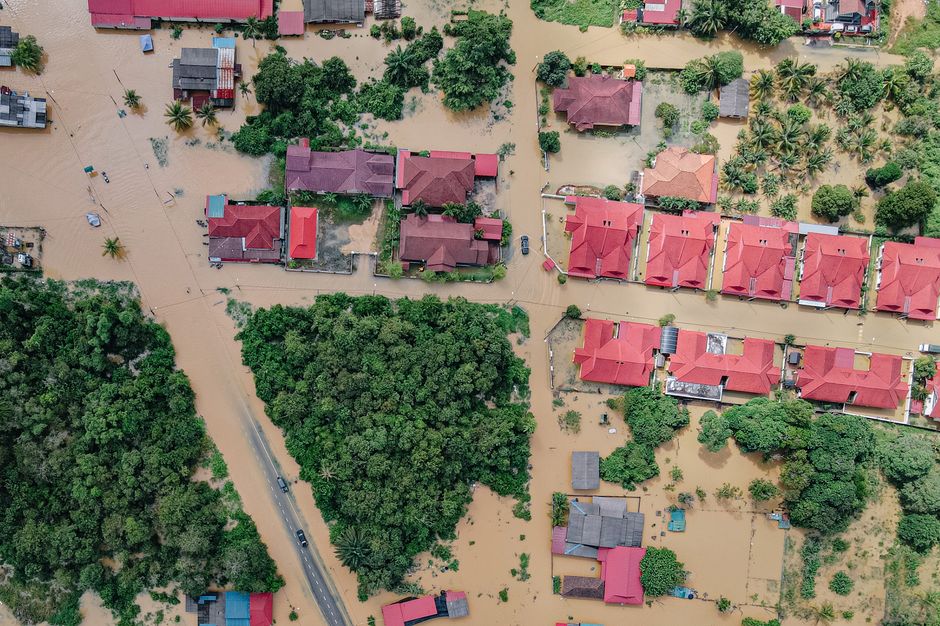
Flood is the most famous one, and still the most misunderstood. A pipe bursts inside your wall: covered. A river crests and sends three inches of water across your living room: not covered, not even a little, regardless of which insurer you’re with. The National Flood Insurance Program (NFIP) exists precisely because private carriers universally exclude flood damage, and the Insurance Information Institute confirms that standard homeowners policies don’t cover flooding from external water sources. Yet as of July 2026, roughly 6% of U.S. homeowners carry separate flood coverage. That number has barely moved in years.
Earthquake is the same story. If you live in California, the Pacific Northwest, or along the New Madrid Seismic Zone running through Missouri and Arkansas, you need a separate policy or endorsement. Period. The standard policy won’t cover the cracked foundation or the collapsed chimney if the cause was seismic. Some carriers offer endorsements; the California Earthquake Authority is the largest provider for that state. Prices vary enormously by soil type and proximity to fault lines.
Here’s the one that genuinely surprised me early in my career: sewer and drain backup. A backed-up sewer line fills your basement with, let’s say, material you’d prefer not to think about. Your standard policy almost certainly excludes it. The good news is that backup coverage is usually available as an add-on endorsement for somewhere between $40 and $120 a year, depending on your carrier and location. I’d call that one of the better values in home insurance. I’ve seen backup claims that ran past $30,000 in remediation and personal property loss.
Gradual Damage: The Exclusion the Industry Leans On Hardest
Helpful resource: Kidde 21005779 Pro 2.5lb ABC Fire Extinguisher is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
Read your policy’s exclusions section and you’ll find language like “continuous or repeated seepage,” “wear and tear,” “deterioration,” and “latent defect.” These phrases collectively do a lot of heavy lifting for insurance companies. If your roof has been slowly leaking for two years and the damage finally becomes impossible to ignore, an adjuster is going to look very carefully at whether this was a sudden, accidental loss (potentially covered) or a gradual accumulation (not covered).
I thought for years that this was a gray area open to negotiation. It is, sometimes. But insurers have gotten better at using inspection reports, satellite imagery, and contractor testimony to establish timelines. If your gutters haven’t been cleaned since 2021 and there’s obvious rot behind the fascia board, that’s not going to look like sudden damage.
The practical upshot: document maintenance. Take photos twice a year. Keep receipts from roofers, plumbers, HVAC techs. A $4,000 claim you can document as sudden will get paid. The same claim without records might not.
Worked example 1: Homeowner in suburban Atlanta notices ceiling staining in 2025, patches it herself, doesn’t call her insurer. In spring 2026 the roof deck is structurally compromised. Adjuster finds evidence of two-plus years of water intrusion. Claim denied under the “gradual damage” exclusion. Repair cost: roughly $19,400 out of pocket. Had she called after the first sign and had a roofer document the cause as a wind-lifted shingle rather than long-term neglect, the claim would likely have gone differently.
Mold, Rot, and the Words Insurers Love
Mold is its own battlefield. Most policies cover mold only when it results directly from a covered peril, and only if you took “reasonable steps” to mitigate it promptly. That second part is where claims die. If a pipe burst in January and you’re filing a mold claim in June, expect questions about why it took five months. Reasonable mitigation generally means calling a water remediation company within 24 to 72 hours of discovering water damage, not when it becomes convenient.
Dry rot gets even less sympathy from carriers. It’s treated essentially as a maintenance failure across the board, which is usually accurate. Still, I’ve seen homeowners surprised that their crumbling porch posts aren’t covered after a storm peels off the paint and exposes the damage underneath. Storm didn’t cause the rot. It just revealed it.
Ordinance or Law: The Expensive One Nobody Talks About
Here’s the exclusion that produces some of the largest unexpected out-of-pocket costs I’ve seen. Let’s say your kitchen catches fire and causes $80,000 in damage. Your policy covers $80,000 in repairs, great. But your house was built in 1978, and current building codes require upgraded electrical panels, fire-rated drywall, and a different egress window configuration than what was originally there. Those upgrades might run another $15,000 to $25,000. The standard policy pays to restore what you had. It does not pay to bring you up to code.
Ordinance or law coverage is an endorsement that fills this gap. It’s not expensive, typically in the range of 5% to 15% of your dwelling coverage amount as a limit, and the premium addition is usually modest. If your home was built before the 1990s, I’d consider this one non-negotiable.
Worked example 2: Homeowner in Portland, Oregon, 1962 construction, suffers a partial fire loss. Covered damage: $67,000. Code-upgrade requirements to obtain a rebuild permit: an additional $22,500 for updated wiring and seismic strapping. She had no ordinance or law endorsement. Net shortfall: $22,500. She’d been with the same carrier for nine years and never knew this gap existed.
A Quick Look at Common Exclusions Across Policy Types
| Exclusion | Standard HO-3? | Covered By | Notes |
|---|---|---|---|
| Flood | No | NFIP or private flood policy | Separate policy required; 30-day waiting period typical |
| Earthquake | No | EQ endorsement or separate policy | California Earthquake Authority is common in CA |
| Sewer/drain backup | No | Endorsement (often $40-$120/yr) | One of the best-value add-ons available |
| Mold (non-sudden) | No | Generally uninsurable; prevention is the answer | Only sudden-source mold may qualify |
| Gradual damage/wear | No | Uninsurable; maintenance is the answer | The most common denial reason in my experience |
| Ordinance or law costs | No | Ordinance or law endorsement | Critical for pre-1990s homes |
| Home business equipment | Limited ($2,500 cap typical) | Home business endorsement or BOP | Standard limit rarely matches actual value |
| Intentional damage | No | Uninsurable | Includes damage by household members |
| Pets/animal liability | Varies by breed/animal | Umbrella policy may help | Many policies exclude specific dog breeds |
| Power outages (food spoilage) | Often excluded | Endorsement available from some carriers | Usually modest sublimit, around $500 |
Home-Based Business: The Coverage Most People Overlook
As of July 2026, close to a third of U.S. households include someone who works from home at least part of the time, and a meaningful share run actual businesses from their residence. Standard policies are not built for this. The typical personal property coverage on a home policy caps business equipment at around $2,500. If you have a podcast studio, video production setup, or even just a serious photography rig, you’re probably uninsured for most of it.
Business liability is a harder problem. If a client visits your home and slips on your porch, a standard homeowners liability clause may not cover it, because the injury occurred in the course of a business activity. Your state’s insurance department website (findable through the NAIC’s state map) can point you toward licensed agents who specialize in home-based business endorsements or separate business owner’s policies.
Worked example 3: Freelance video editor in Austin carries a standard HO-3. Three cameras, two monitors, a NAS drive setup, and professional lighting: total replacement value around $18,000. Policy would cover $2,500. An endorsement specifically for in-home business equipment was available from her carrier for about $340 a year. She didn’t know it existed until a reader (okay, her sister, who emailed me after reading a piece I wrote in early 2026) mentioned it. The endorsement was added retroactively during renewal.
Sources
- Insurance Information Institute (III): Policy structure, standard exclusions, flood and earthquake coverage statistics
- National Association of Insurance Commissioners (NAIC): State insurance department contacts and consumer resources
- Federal Emergency Management Agency (FEMA) / NFIP: National flood insurance enrollment rates and policy details
- California Earthquake Authority: Earthquake insurance data and pricing for California residents
- III “Homeowners Insurance Basics” (current as of 2026): Breakdown of HO-3 form coverage and standard exclusion categories
Photo: Pok Rie via Pexels
This article is for general informational purposes only and does not constitute insurance advice. Coverage details, exclusions, and costs vary significantly by insurer, policy type, and location. Always review your policy documents and consult a licensed insurance professional for advice specific to your situation.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Kidde 10-Year Battery Smoke & CO Detector (~$32), Dual smoke and carbon monoxide detector with 10-year sealed battery, no battery replacement needed for a decade.
- Ring Alarm 8-Piece Security Kit (~$199), Professional-grade DIY home security system with optional 24/7 monitoring, top way to qualify for insurance discounts.





