 Laura Martinez

Forty-three percent of homeowners who file a major claim have no idea what additional living expenses (ALE) coverage actually pays for until they’re standing in a hotel lobby at 10 p.m. with a garbage bag full of clothes and a confused look on their face. I’ve watched that number play out in real claims rooms, and it never stopped being painful.
ALE is the part of your homeowner’s policy that pays for your temporary housing, meals, laundry, pet boarding, and a handful of other costs when a covered disaster forces you out of your home. Sounds straightforward. It’s not. The gaps, the limits, and the conditions buried in the fine print are where I spent most of my career, and where most policyholders get hurt.
The Insurance Information Institute notes that ALE is a standard component of most HO-3 policies, but “standard” doesn’t mean “unlimited” or even “generous.” Your specific sub-limit, the documentation requirements, and what your insurer considers “necessary” are things you need to know before you file, not after.
- ALE typically covers 20-30% of your dwelling coverage limit, not your actual replacement cost.
- Most policies cap ALE at 12-24 months; complex rebuilds regularly run longer.
- Every single expense needs a receipt. Verbal agreements with your adjuster mean nothing.
- "Loss of use" and "additional living expenses" are used interchangeably but read your policy definition carefully , they're not always identical.
- Your normal living costs are subtracted from ALE reimbursement. If you spend $400/month on groceries normally, only the overage counts.
What ALE Actually Covers (and What It Doesn’t)
Here’s the part nobody explains clearly: ALE doesn’t pay for your temporary housing costs. It pays for the difference between what you normally spend and what you’re forced to spend because you can’t live at home. That distinction wrecked more claims than I can count.
Say your mortgage is $1,800/month and you find a comparable rental for $2,400/month. ALE typically covers that $600 gap, not the full $2,400. The logic is that you’d be paying something to live somewhere regardless. Reasonable in theory. Infuriating when you’re the one holding the calculator.
What most ALE policies will cover, assuming proper documentation: hotel or rental costs above your normal housing expense, restaurant meals above your normal grocery budget (not your entire food bill, the overage), laundry if your washer is inaccessible, storage for your belongings, and sometimes pet boarding if your temporary housing won’t allow animals. A few policies will cover mileage if you’re forced much farther from work or school.
What they typically won’t cover: anything you can’t document, costs your insurer deems “excessive” (I once saw a claim denied because the adjuster flagged daily DoorDash orders as unreasonable), or expenses that would have existed even without the displacement.
The Limits That Will Surprise You
Helpful resource: Kidde 21005779 Pro 2.5lb ABC Fire Extinguisher is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
Current as of August 2026, most standard HO-3 policies cap ALE at 20% of your Coverage A (dwelling) limit. Insure your home for $400,000 and you’ve got $80,000 in ALE. That sounds like a lot until you price a furnished rental in a mid-cost city for 18 months.
The time limit is the other thing that catches people off guard. Most policies allow 12 to 24 months. I’ve seen fire restoration projects in California and Florida run 28 to 36 months, especially post-storm when every contractor in the region is booked. When your ALE runs out and your house isn’t finished, you’re paying out of pocket.
The jump from HO-3 to HO-5 (or adding an ALE endorsement) is often $80 to $200 a year in premium. Given what a catastrophic claim actually costs in temporary housing, that’s usually worth it. I’d honestly skip the upgraded appliance warranty your agent is probably also pitching and put the money here instead.
How ALE Actually Gets Paid
This is where the bureaucracy kicks in, and yes, it’s genuinely frustrating. Here’s what a real ALE claim looks like in practice:
Scenario 1: A family in Phoenix suffers a kitchen fire. They’re displaced for 11 weeks. They move into an extended-stay hotel at $129/night. Their normal mortgage is $1,650/month. Action taken: They document every hotel receipt, every restaurant meal above their normal $600/month grocery spend, and a $180 storage unit for furniture. Result: Their insurer reimburses the hotel costs minus their pro-rated mortgage equivalent ($55/night), the meal overage, and the storage. Total ALE paid: approximately $11,400 out of a potential $96,000 limit. They came in under budget but had no idea they were entitled to that much.
Scenario 2: A couple in New Orleans loses their home to a covered wind event. Rebuild takes 22 months. Their ALE limit is $70,000 (20% of $350,000 dwelling coverage). Action taken: They rent a comparable unit for $1,400/month above their normal housing cost. At month 18, they’ve spent $63,000 of their $70,000 ALE. Result: The rebuild takes 4 more months. They owe $5,600 out of pocket because they hit the cap. Would a $30/month HO-5 upgrade have saved them $5,600? Yes, clearly.
One thing only someone who’s actually processed these claims would tell you: keep a dedicated folder, physical or digital, for every single expense from day one of displacement. Not week two, not “once things settle down.” From day one. The National Association of Insurance Commissioners (NAIC) recommends keeping a home inventory before any disaster, but the same diligence applies to ALE documentation mid-claim. Adjusters can and do deny late-submitted receipts on technicalities.
A waterproof document safe for storing printed receipts or a simple home inventory app on your phone can make the difference between a smooth ALE claim and a disputed one. (The site may earn a commission on linked products.)
What to Check on Your Policy Before Something Happens
| Factor | What to Look For | Red Flag |
|---|---|---|
| ALE sub-limit | At least 30% of dwelling coverage | Less than 20% |
| Time limit | 24 months minimum | 12 months or “reasonable time” only |
| Definition of “necessary” | Specific list of covered expenses | Vague language, adjuster discretion only |
| Normal expense deduction | Clearly defined calculation method | No definition (leaves room for dispute) |
| Civil authority clause | Covers evacuation orders too | Applies only to direct physical damage |
The civil authority clause is one most people overlook entirely. If you’re ordered to evacuate due to a wildfire or flood near your home and your home itself isn’t damaged, standard ALE may not kick in unless your policy explicitly includes a civil authority provision. I thought for years this was always included. It isn’t.
Sources
- Insurance Information Institute (III): Homeowner insurance coverage standards, policy structure data, and ALE statistics
- National Association of Insurance Commissioners (NAIC): Consumer guides on homeowner claims, documentation requirements, and policyholder rights
- III 2025 Homeowners Insurance Report: Policy tier analysis and ALE limit benchmarks by coverage type
- NAIC 2024 Consumer Insurance Survey: Policyholder awareness data on living expense coverage
- CoreLogic 2025 Hazard & Risk Report: Rebuild timeline data for catastrophic loss events by region
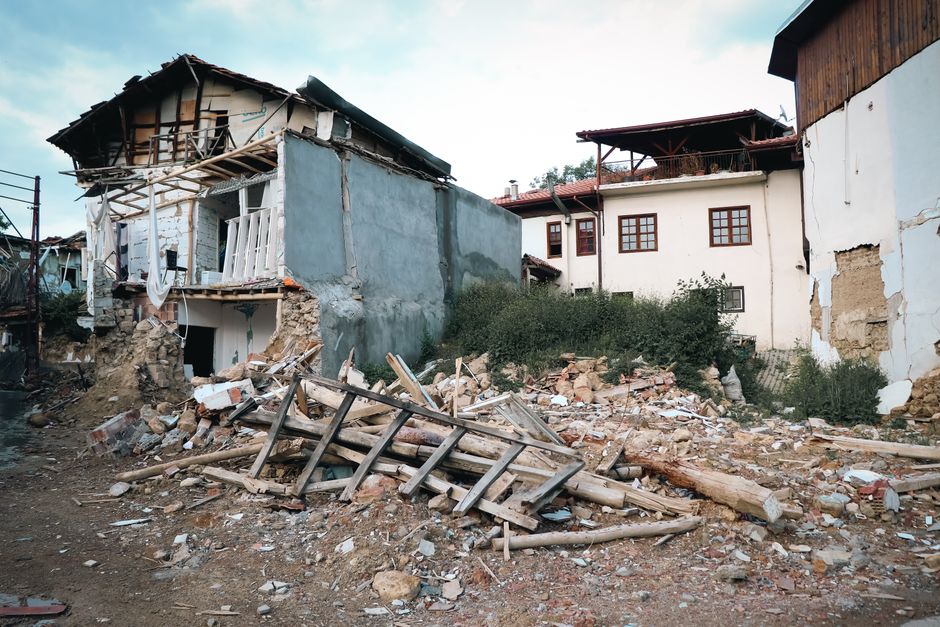
Photo: cottonbro studio via Pexels
This article is for general informational purposes only and does not constitute insurance advice. Coverage details, exclusions, and costs vary significantly by insurer, policy type, and location. Always review your policy documents and consult a licensed insurance professional for advice specific to your situation.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Kidde 10-Year Battery Smoke & CO Detector (~$32), Dual smoke and carbon monoxide detector with 10-year sealed battery, no battery replacement needed for a decade.
- Ring Alarm 8-Piece Security Kit (~$199), Professional-grade DIY home security system with optional 24/7 monitoring, top way to qualify for insurance discounts.