 Kevin Park
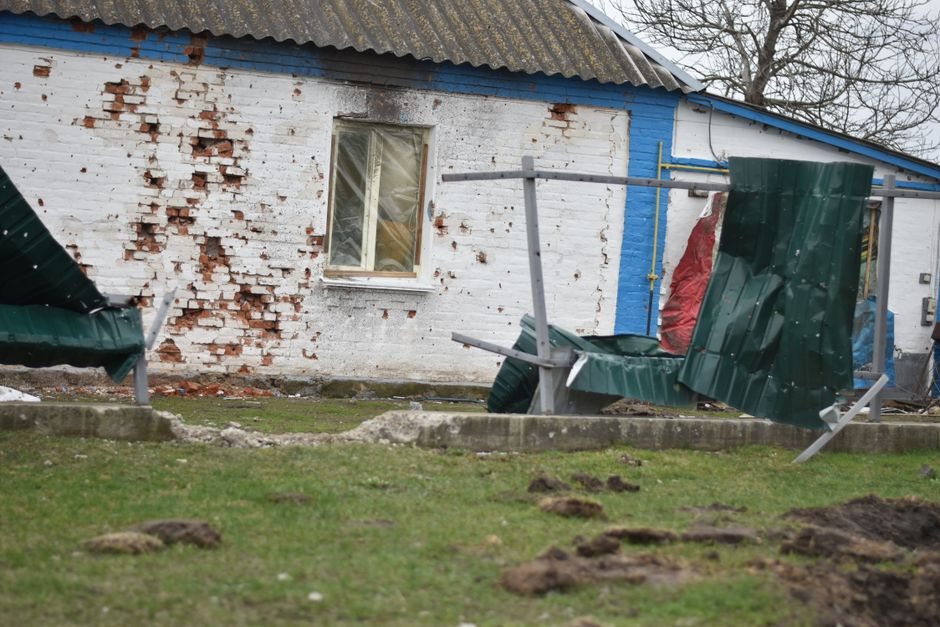
Most people find out what their policy actually covers at the worst possible moment: standing in a gutted kitchen, smoke smell still in the walls, waiting on a claims adjuster who’s about to deliver news they weren’t prepared for.
I’ve seen it happen dozens of times. A homeowner files a claim after a fire or burst pipe, fully expecting the insurer to hand them enough money to restore what they had. Instead they get a check that covers maybe 60 cents on the dollar. The conversation that follows is painful, and honestly, it’s almost always preventable. The culprit, nine times out of ten, is a misunderstanding of four words that appear somewhere in every homeowners policy: actual cash value and replacement cost.
These aren’t just insurance jargon. They represent two fundamentally different promises your insurer is making to you, and the gap between them can be tens of thousands of dollars.
- Actual cash value (ACV) pays what your property was worth at the time of loss, after depreciation.
- Replacement cost value (RCV) pays what it costs to buy or rebuild the same item new today.
- The gap between ACV and RCV on a 10-year-old roof can easily exceed $8,000–$15,000 on a mid-size home.
- Replacement cost coverage typically costs 10–15% more in annual premium, which usually pays for itself after one significant claim.
- Check whether your policy applies RCV or ACV separately to your dwelling, personal property, and detached structures.
What “Actual Cash Value” Really Means
Here’s the part that trips people up: ACV isn’t a bad-faith trick. It’s a coherent valuation method. It just happens to be the one that benefits the insurer more than you.
The formula is essentially: replacement cost minus depreciation. Depreciation is calculated based on the item’s expected lifespan and its age at the time of the loss. Your 12-year-old roof gets depreciated. Your 8-year-old refrigerator gets depreciated. Your 15-year-old hardwood floors get depreciated. What sounds like a fair accounting principle turns into a rude surprise when you realize that a roof with a 20-year lifespan, damaged at year 12, gets paid out at 40% of its replacement value.
Worked example: A homeowner in suburban Ohio has wind damage to a shingle roof. Contractor estimate to replace it: $14,200. The roof is 10 years old with a 25-year expected lifespan, so the insurer depreciates it 40%. ACV payout: $8,520, minus the deductible. The homeowner is out of pocket for the rest, or they defer repairs. Neither option is great.
What most people don’t realize is that depreciation schedules vary by insurer and category. Some carriers use “functional obsolescence” arguments on older appliances. I once reviewed a claim where an adjuster applied 70% depreciation to a perfectly functional but old furnace because replacement parts were no longer manufactured. The policyholder got $420 on a unit that cost $1,400 to replace. It was technically defensible. It also felt like a gut punch.
Replacement Cost Coverage: The Real Promise
Helpful resource: Kidde Carbon Monoxide and Propane Detector is a top-rated option for this. (As an Amazon Associate this site earns from qualifying purchases.)
RCV coverage pays the actual cost to replace or rebuild with materials of similar kind and quality, without deducting for age or wear. That’s the core difference. You’re not being paid for what you had. You’re being paid for what it costs to have it again.
One thing I always tell people: even on replacement cost policies, most insurers don’t hand you the full RCV check upfront. Standard practice is to release the ACV portion immediately, then issue a “recoverable depreciation” payment once you’ve completed repairs and submitted documentation. You need receipts. You need to actually do the work. If you pocket the initial check and skip the restoration, you typically forfeit the holdback.
Worked example: Same Ohio roof, same $14,200 estimate, but this time the homeowner has RCV coverage. Initial check: $8,520 (the ACV amount). They hire the contractor, submit the final invoice and completion photos, and the insurer releases $5,680 in recoverable depreciation. Total received: $14,200, minus the deductible. That’s the policy working as intended.
ACV vs. RCV: Side by Side
The numbers matter a lot here, so here’s a plain comparison across common claim scenarios.
| Scenario | Item Age | Replacement Cost | ACV Payout | Gap |
|---|---|---|---|---|
| Asphalt shingle roof | 12 years (25-yr lifespan) | $14,200 | ~$8,520 | ~$5,680 |
| Central HVAC unit | 8 years (15-yr lifespan) | $6,800 | ~$4,053 | ~$2,747 |
| Kitchen appliances (fire) | 10 years (15-yr lifespan) | $4,500 | ~$1,500 | ~$3,000 |
| Personal electronics | 4 years (5-yr lifespan) | $2,200 | ~$440 | ~$1,760 |
| Upholstered furniture | 7 years (10-yr lifespan) | $3,600 | ~$1,080 | ~$2,520 |
These are estimates based on common depreciation schedules, current as of July 2026. Your insurer’s exact depreciation tables may vary, and you have the right to request them.
The premium difference for upgrading from ACV to RCV is typically in the range of 10–15% annually, based on figures cited by the Insurance Information Institute. On a policy running $1,400 a year, that’s roughly $140–$210 more per year. After even one significant roof or appliance claim, you’ve recovered that cost many times over.
The Part Nobody Tells You About Your Personal Property
Here’s where I made a mistake myself, early in my career as a claims reviewer. I assumed that if a homeowner had replacement cost on their dwelling, they had it on everything. That’s wrong, and it trips up more policyholders than almost any other misunderstanding I encountered.
Many standard policies cover the dwelling structure under RCV but default personal property (your furniture, clothes, electronics, appliances) to ACV unless you specifically add or upgrade that coverage. You can have a $400,000 RCV policy on your house and a very disappointing payout on the $60,000 worth of stuff inside it.
Read the declarations page. Find the section labeled “Coverage C” or “Personal Property.” Look for the words “replacement cost” or “actual cash value.” If you’re not sure what you have, call your agent and ask directly: “Does my personal property coverage pay replacement cost or actual cash value?” Don’t let them answer with marketing language. Push for a yes or no on that specific question. Your state’s insurance department can also help you understand what disclosures insurers are required to provide in your state.
One practical step that costs nothing: create a home inventory. Film a slow walkthrough of every room, open drawers, show model numbers on appliances. Store that video off-site or in cloud storage. When I was processing claims, homeowners with good documentation recovered significantly more, faster, because there was nothing to dispute. If you want a more organized version, apps like Encircle or the III’s free Know Your Stuff tool work well. (Some people keep physical documents in a fireproof safe like the AmazonBasics document safe – the site may earn a commission on that link.)
Extended and Guaranteed Replacement Cost
One more layer worth knowing about, especially in areas where construction costs have been climbing: extended replacement cost and guaranteed replacement cost riders.
Extended replacement cost adds a buffer, typically 25–50%, above your policy’s dwelling coverage limit. So if your home is insured for $350,000 but rebuilding costs $420,000 after a major loss, an extended RCV rider at 25% would cover up to $437,500. Guaranteed replacement cost takes it further, promising to cover full rebuild costs regardless of the limit, though this coverage has become harder to find and pricier since regional building material costs spiked.
Worth getting? Honestly, I’d say yes to extended RCV for most homeowners, especially if you bought your policy more than two years ago and haven’t had a coverage review since. Construction costs have moved enough in recent years that many existing policy limits are quietly undercovered. The average home rebuild cost per square foot has risen sharply in many markets. A policy that looked adequate in 2022 may be short today.
Worked example: A homeowner in coastal North Carolina carried $280,000 in dwelling coverage, which matched the purchase price. After a hurricane, the actual rebuild quote came in at $367,000, in part due to material and labor shortages. She had a 25% extended RCV rider, which covered up to $350,000. She was still short $17,000. Without the rider, she’d have been $87,000 short. The rider didn’t fully save her, but it meaningfully reduced the gap.
Sources
- Insurance Information Institute (III): Industry data on homeowners coverage types, depreciation, and premium ranges
- National Association of Insurance Commissioners (NAIC): Regulatory standards for claim handling and consumer rights by state
- III “Know Your Stuff” Home Inventory Tool: Free documentation resource for homeowners
- Marshall & Swift/CoreLogic Residential Cost Handbook: Industry-standard depreciation and replacement cost tables used by adjusters
- NAIC 2025 Homeowners Insurance Report: Aggregate data on coverage gaps, ACV vs. RCV policy distribution
Photo: Serhii Bondarchuk via Pexels
This article is for general informational purposes only and does not constitute insurance advice. Coverage details, exclusions, and costs vary significantly by insurer, policy type, and location. Always review your policy documents and consult a licensed insurance professional for advice specific to your situation.
Recommended Resources
Disclosure: As an Amazon Associate, we earn a small commission from qualifying purchases at no extra cost to you. We only recommend products that genuinely support the topics covered in this article.
- Kidde 10-Year Battery Smoke & CO Detector (~$32), Dual smoke and carbon monoxide detector with 10-year sealed battery, no battery replacement needed for a decade.
- Ring Alarm 8-Piece Security Kit (~$199), Professional-grade DIY home security system with optional 24/7 monitoring, top way to qualify for insurance discounts.





